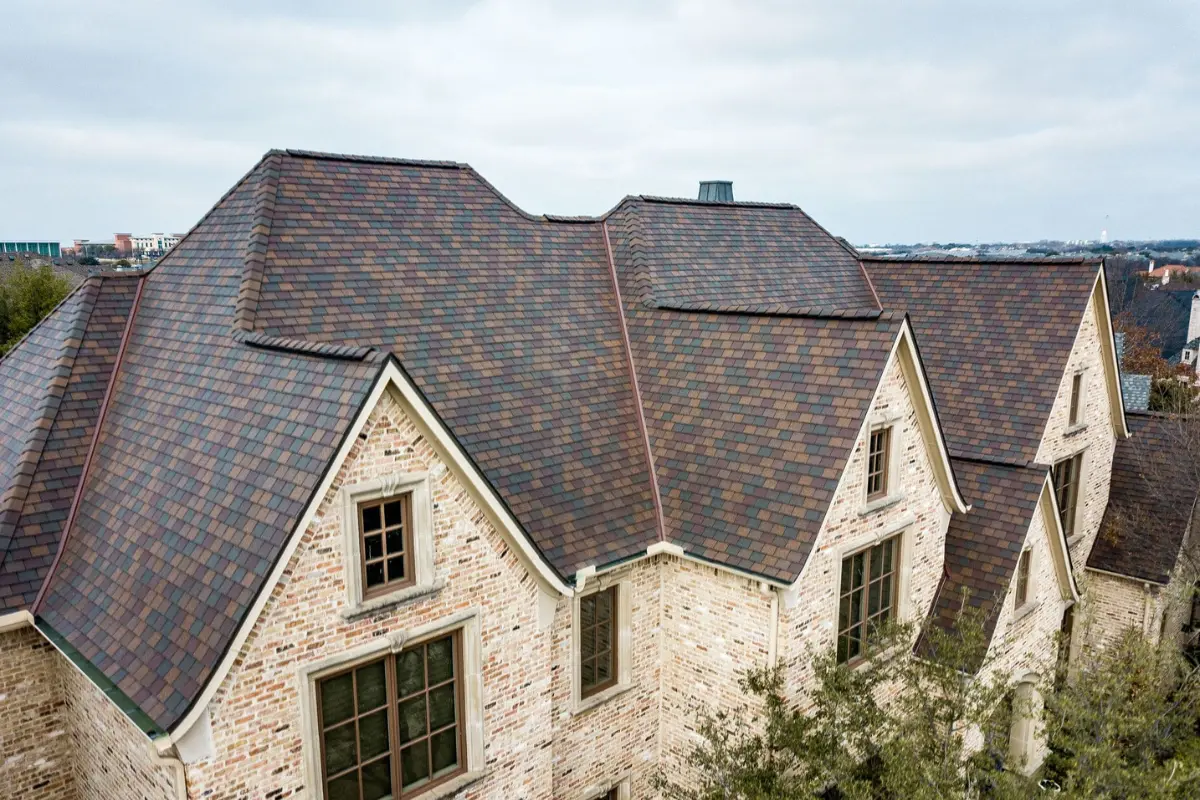
Hail and storm insurance claims in San Antonio, translated into plain English.
Most homeowners file 1–2 roof claims in their lifetime. Here’s everything you wish you knew before the first one.
The 6-step claim process
How hail claims work in San Antonio specifically
Bexar County sits in Texas's hail alley — that changes what to expect from the claims process.
Bexar County averages 2–4 significant hail events a year, mostly March through May, so most San Antonio roof claims start the same way: a storm passes, and the question becomes whether the damage is functional or cosmetic. That distinction, not the size of the hail, is what determines whether the claim gets paid.
San Antonio's spring hail season also means adjusters here see a high volume of claims in a short window. After a widespread event, carriers deploy catastrophe-team adjusters who may not know your specific neighborhood's typical roof age or construction — an independent inspection from a local roofer before the adjuster arrives carries real weight in that situation.
See our hail damage guide for how to tell functional damage from cosmetic marks, and how big the hail needs to be before it's worth a claim.
The single most important rule
Never sign a contract with a roofer before the insurance decision. Some contractors will ask you to sign an “assignment of benefits” (AOB) or a contingent contract on day one. Don’t. In Texas, you have the legal right to control your claim and your contractor separately.
Watch out for storm chasers
After every major hail event, out-of-state contractors flood Central Texas. They knock doors, offer to “waive your deductible,” and disappear before warranty issues surface. Waiving the deductible is illegal — and you’re the one holding the bag.
Complaint or fraud report?
If you disagree with a claim denial or the amount your insurer is paying, that is a complaint to the Texas Department of Insurance. If you suspect a criminal act, such as a padded or false claim or a deductible scheme, that is a fraud report. Not sure which? Call TDI's Help Line at 800-252-3439, Monday–Friday, 8 a.m.–5 p.m. Central. How to report insurance fraud in Texas.
Use a licensed, local, manufacturer-certified roofer. Every time. The nuance worth knowing: Texas issues no statewide roofing contractor license, but many municipalities in the San Antonio metro and across Central Texas require contractor registration or licensing at the city level, and that local standing is how permits get pulled. A contractor who cannot pull a permit in your city is telling you something. Alongside that, check for a permanent local address you can drive to, current general liability and workers' compensation certificates, manufacturer certifications you can verify directly with the manufacturer, and a track record you can look up. Atrium's own City of San Antonio registration is HIC-24-00295, mandatory here rather than optional. Ask to see it, and ask anyone else quoting you for theirs. Atrium also holds roofing contractor licenses with the City of Universal City (No. REG1946), the City of Live Oak (No. 11093), the City of Alamo Heights (No. 355930), the City of Windcrest (No. 2810), and the City of Schertz. In Universal City, Live Oak, Alamo Heights and Windcrest the license is mandatory, and the city stops work without it. Here is the compliance detail, including the laws that do apply.
Insurance FAQs
Let's document your roof.
No pressure, no obligation. Calls answered 24/7 in English & español by Alex, our AI specialist · Get an engineer-led 53-point roof inspection, not a sales pitch.